Why US banks are opening new branches, not closing them

US banks are reopening physical branches to attract deposits, strengthen customer relationships and gain market share, showing that face-to-face banking remains valuable despite the shift to digital services.

Jonathan Shapiro

Why US banks are opening new branches, not closing them

October 14, 2026
US banks are reopening physical branches to attract deposits, strengthen customer relationships and gain market share, showing that face-to-face banking remains valuable despite the shift to digital services.
Read Transcript

When Ravi Chopra last travelled from his base in Miami to Australia, back in 2023, the US banking system was in turmoil.

‍

The Silicon Valley Bank crisis had triggered a crisis of confidence and a wave of shotgun deals to save lenders at risk of deposit runs. Chopra's financials-focused hedge fund, Azora Capital, had bet against SVB in its own version of a big short.

‍

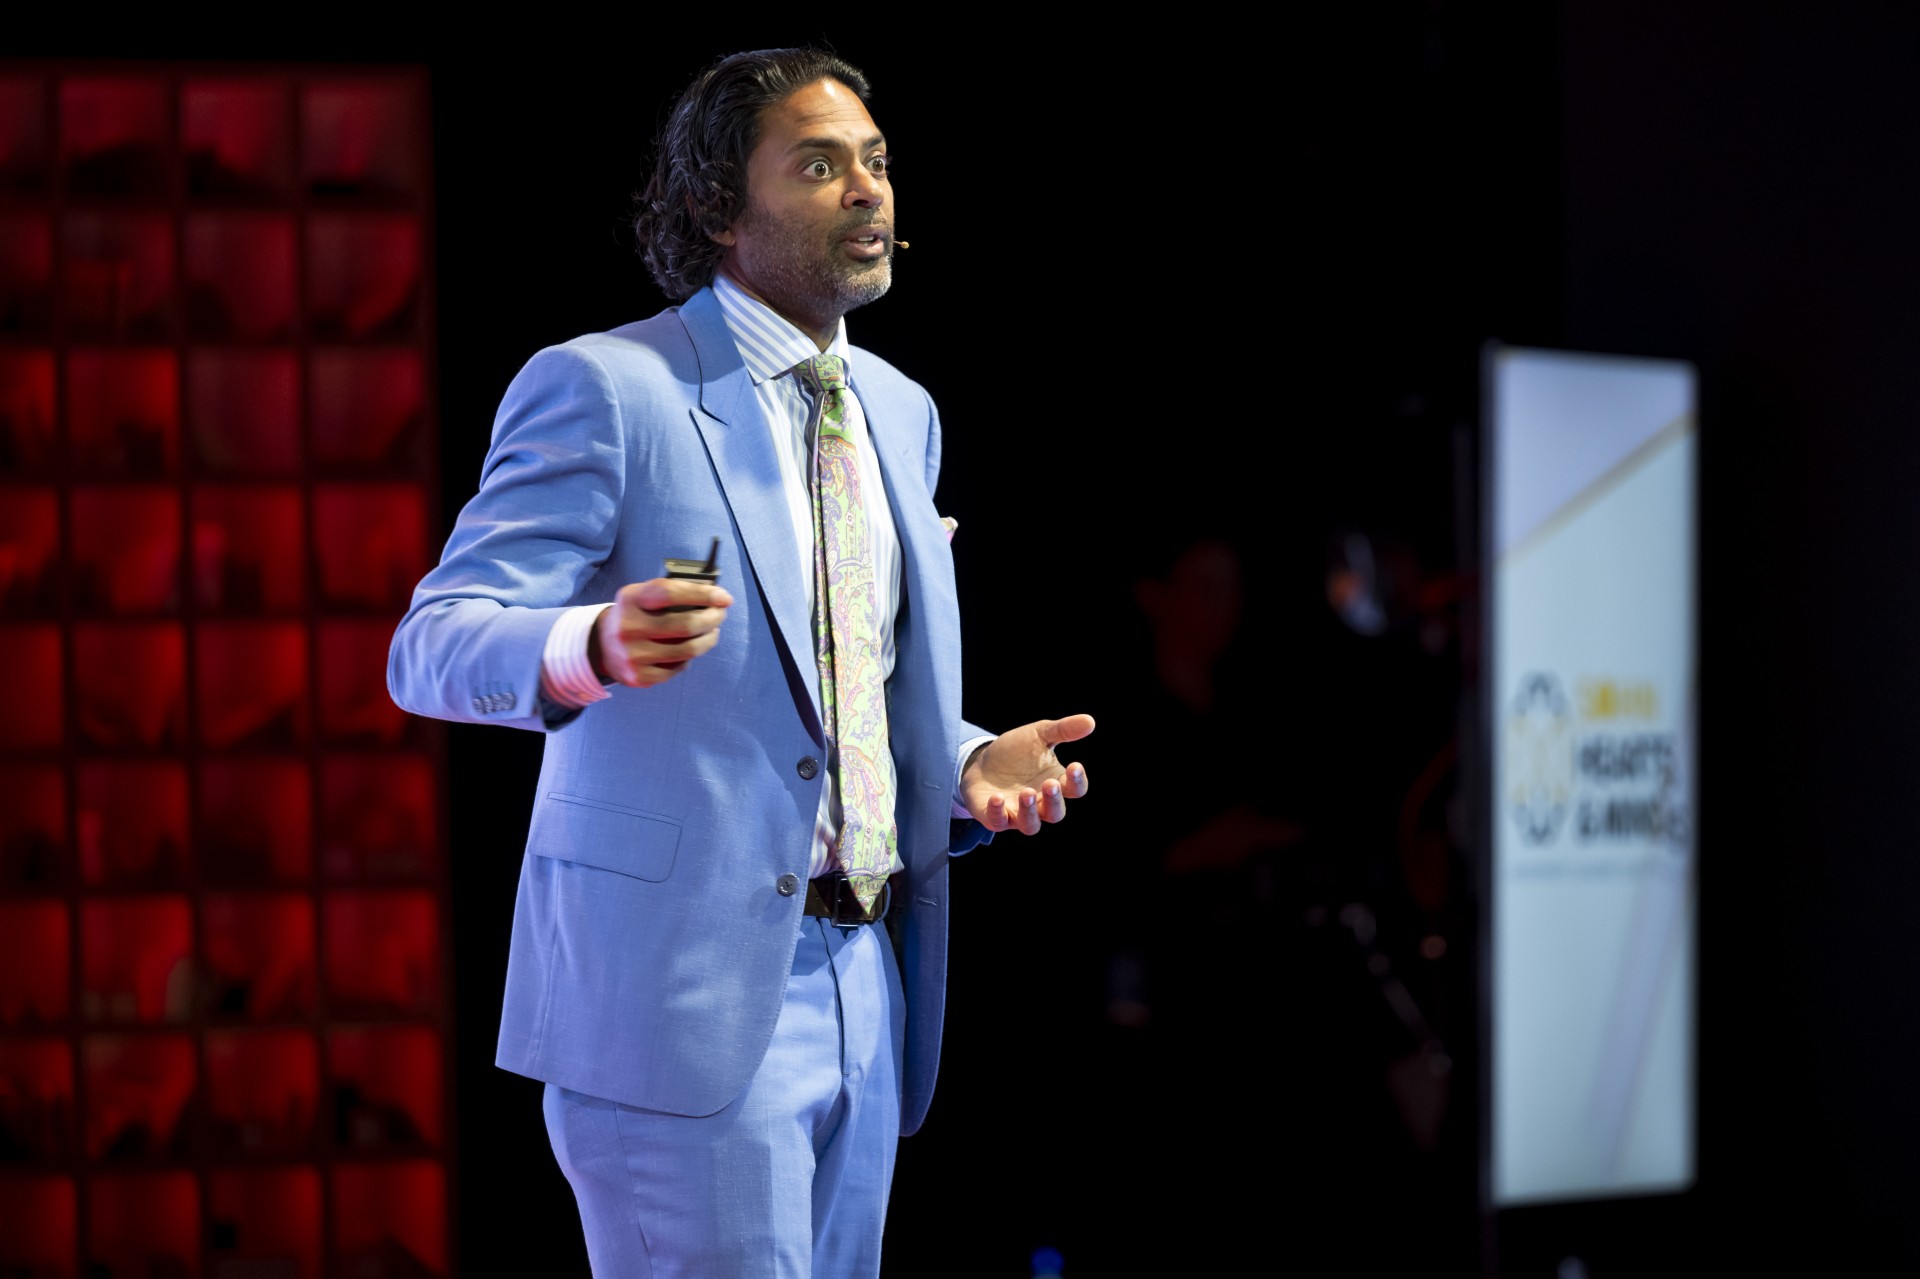
Three years later, Chopra is returning to the region to pitch a stock at the Sohn Hearts & Minds investment conference in Queenstown, New Zealand. This time the US banking sector has never been stronger.

‍

His 2023 conference pick, Webster Bank, doubled in value and has been bought by Santander, while high interest rates and low loan losses have lifted profitability across the sector to record highs. It was a backdrop Chopra described as ‘‘better than nirvana''.

‍

Azora, which has US2.5billion (3.6 billion) of assets under management, switched from a short position in US banks to a long position. Now, it's more neutral, and if Chopra has one big prediction, it's that a wave of mergers and acquisitions in the banking sector awaits. ‘‘In the last 15 years, we've seen bank CEOs pushing well past retirement age,'' he explains. They'd been through a pandemic, zero interest rates, a regional banking crisis and tough regulation, and now with projected profits above their peaks, he reckons they'll decide ‘‘it's time for me to hit the bid and go play some golf''.

‍

The generational shift in corporate ownership extends beyond the banks. Chopra says the sector faces challenges relevant to the big Australian banks, including higher funding costs as depositors chase better deals driven in part by neo-bank competitors. The other is a peak in favourable regulationa reminder that changes in the political environment can have a bearing on the operating backdrop for banks.

‍

So why are deposit costs likely to trend higher in the US? Chopra says it's a mixture of ‘‘technology, awareness and competition'' that will force more savers to be more proactive in getting the highest rates on their savings.

‍

The threat of artificial intelligence driving this trend is making headlines. Chopra says he has mixed views on the potential for AI agents to encourage more switching among US savers into higher-yielding deposits. He points to JPMorgan chairman Jamie Dimon's comments that responsibility switches from the bank to the customer if they hand power to robots to manage their cash.

‍

A far more relevant and near-term threat is neo-bank or digital competitors such as Revolut, which operate with lower costs and overheads compared with their larger rivals. ‘‘They don't have a back book [of deposits] to reprice, and so they can be very aggressive. That's definitely one of the reasons I see a deposit cost going up over time.''

‍

Those comments can be applied to the battle between Macquarie and Commonwealth Bank, as the former's deposit competitiveness drives its market share grab. That in turn has led to a political debate about whether Macquarie and other digital banks should compensate the broader banking sector, which services the public through expensive national branch networks.

‍

On the matter of branches, Chopra has actually noticed an interesting and counter-intuitive development: the big US banks are actually opening, not closing, branches, reversing a decadelong trend.

‍

‘‘What banks have found is that a large swath of customers like the idea of knowing there's a bank branch they can go to, even if they're not going to go to it, and even if it's a little far away,'' he says. ‘‘The bank branch does provide some amount of advertising, and a feeling of trust and confidence.''

‍

That banks would ultimately realise that branches were far more valuable than simply the service they provide was predicted by former US Federal Reserve governor Jeremy Stein in a speech titled ‘‘Banks as patient debt investors'', way back in 2014.

‍

In that address, Stein explained that even though branches cost about 1.3 per cent of the value of deposits gathered, they could also be considered ‘‘a deliberate effort to build loyalty'' and foster ‘‘deposit stickiness'', which is the underrated secret sauce of a profitable bank.

‍

A bank with sticky deposits wins in two crucial ways: it has lower funding costs than its peers and, crucially, it has more flexibility to write, and hold on to, longer-term profitable loans because the capital source is stable.

‍

‘‘This is a truism [in finance] that it's easy to give money away. On the asset side, you can always make loans, and you can always buy securities,'' says Chopra. ‘‘The hard part, and the true value, of the bank is on the deposit side.''

‍

That brings us to the next big topic in US and global finance: private credit. It turns out the sector was doing the easy part of finance in giving money away as it grew by $US1 trillion in five years.

‍

‘‘If you are growing materially faster than the market, you are almost always taking some unintended credit risk,'' Chopra said. ‘‘You're mispricing risk in some way, and that often ends in a credit issue.''

‍

The growth of private credit ate into the lending share of US banks as borrowers accepted higher rates in exchange for faster approval times and looser terms. The banks, however, are sitting pretty.

‍

‘‘The upside is that the banking industry as a whole actually kept their noses clean. They had to follow regulatory guidelines, and credit, as a consequence, has proven to be quite surprisingly strong for a long period of time.''

‍

Now, the banks have been telling the market they're regaining market share from the private credit players who are learning that it's easy to give money away but much harder to secure stable financing.

‍

‘‘The retail products have seen outflows from the private credit industry, and perhaps, as a consequence of that, they're being a bit less aggressive as it relates to competing for loans.''

‍

‍The Australian Financial Review is a media partner of Sohn Hearts & Minds.

‍

This article was originally posted by The Australian Financial Review here. Licensed by Copyright Agency. You must not copy this work without permission.

‍

Disclaimer: This material has been prepared by Australian Financial Review, published on October 14, 2026. HM1 is not responsible for the content of linked websites or content prepared by third party. The inclusion of these links and third-party content does not in any way imply any form of endorsement by HM1 of the products or services provided by persons or organisations who are responsible for the linked websites and third-party content. This information is for general information only and does not consider the objectives, financial situation or needs of any person. Before making an investment decision, you should read the relevant disclosure document (if appropriate) and seek professional advice to determine whether the investment and information is suitable for you.

facebook
linkedin
All
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
November 17, 2023

ARK Founder Wood Backs Bitcoin, Banking On Spot ETF Approval

Tech investment guru Cathie Wood is still a big believer in bitcoin, so it was fitting that she chose Grayscale Bitcoin Trust as her stock pick for the 2023 Sohn Hearts & Minds Investment Leaders Conference.

Read More
IFM Investors small cap specialist Rikki Bannan addresses the Sohn Hearts & Minds Investment Leaders Conference at Sydney Opera House. Picture: Renee NowytargerIFM Investors small cap specialist Rikki Bannan addresses the Sohn Hearts & Minds Investment Leaders Conference at Sydney Opera House. Picture: Renee NowytargerIFM Investors small cap specialist Rikki Bannan addresses the Sohn Hearts & Minds Investment Leaders Conference at Sydney Opera House. Picture: Renee NowytargerIFM Investors small cap specialist Rikki Bannan addresses the Sohn Hearts & Minds Investment Leaders Conference at Sydney Opera House. Picture: Renee Nowytarger
November 17, 2023

Hot Stocks To Ride The Next Healthcare Trends

Healthcare stocks – from sleep apnoea giant ResMed, to cancer diagnostic biotech Telix Pharmaceuticals – were recommended at the Sohn Hearts & Minds Investment Leaders Conference on Friday.

Read More
November 17, 2023

How Daniel Loeb, The Real Bobby Axelrod, Made His Wall Street Billions

When Damian Lewis, the actor who plays the ruthless hedge fund boss in the drama series Billions was looking for inspiration, he sat down with Daniel Loeb.

Read More
November 17, 2023

Investors Sound Warning On Private Equity Timebomb

Institutional investors such as super and pension funds are investing in private equity at “exactly the wrong time,” a top hedge fund manager has warned, as sharply higher interest rates threaten a wave of bankruptcies.

Read More
November 17, 2023

The 12 Hottest Stock Tips From This Year’s Sohn Experts

It might be time to look beyond big names. That was the message from top fund managers, company founders and super funds at the Sohn Hearts & Minds.

Read More
Azora Capital founder Ravi Chopra. Picture: Renee NowytargerAzora Capital founder Ravi Chopra. Picture: Renee NowytargerAzora Capital founder Ravi Chopra. Picture: Renee NowytargerAzora Capital founder Ravi Chopra. Picture: Renee Nowytarger
November 17, 2023

Webster Financial ‘Avoided The Mistakes Of US Bank Failures’

The US financial sector is not without its problems but Ravi Chopra backs Webster Financial Corporation as his stock pick for the 2023 Sohn Hearts & Minds Investment Leaders Conference.

Read More
November 17, 2023

Why Stock Picker Cathie Wood Of ARK Can’t Stand Google

The world’s highest-profile tech investor, Cathie Wood, might be bruised but she is certainly bullish. Nor is she holding back.

Read More
Munro Partners partner and portfolio manager Kieran Moore at the Sohn Hearts & Minds conference in Sydney. Picture: Renee NowytargerMunro Partners partner and portfolio manager Kieran Moore at the Sohn Hearts & Minds conference in Sydney. Picture: Renee NowytargerMunro Partners partner and portfolio manager Kieran Moore at the Sohn Hearts & Minds conference in Sydney. Picture: Renee NowytargerMunro Partners partner and portfolio manager Kieran Moore at the Sohn Hearts & Minds conference in Sydney. Picture: Renee Nowytarger
November 17, 2023

Wise Share Price Could Rise 50pc By 2025, Says Munro Partners

Global growth fund manager Munro has about $4.3bn in funds under management across four global funds, and usually invests in companies that are poised to win from massive structural change.

Read More
November 16, 2023

Hedge Fund Veteran Talks Lowest Moment In Toscafund’s 23-Year Run

Most hedge fund managers brag about their wins and shy away from their losses – Martin Hughes is not most hedge fund managers.

Read More
November 16, 2023

The ‘Armageddon Scenario’ Worrying The Future Fund CIO

Mr Samild shared his thoughts on the bond market – which underpins the returns of other assets – ahead of his appearance at Friday’s Sohn Hearts & Minds charity conference at the Sydney Opera House.

Read More
November 15, 2023

Daniel Loeb’s Wall St Hedge Fund Third Point Raises Bets On Corporate Credit Crunch

An “obsession” around balance sheet strength and debt is creating a new wave of investment bets for the influential Wall Street hedge fund run by Daniel Loeb.

Read More
November 13, 2023

Bond Bullish On Commodity Stocks, Uranium

Mining stocks are poised to rise amid tight supply for key commodities such as copper, nickel and uranium, says Terra Capital founder Jeremy Bond.

Read More
November 13, 2023

This Hedge Fund Manager Is Making A 100-Year Bet On Luxury

European leisure and luxury – a designer handbag, a last-minute flight to Monte Carlo, a stay in a five-star hotel – is where many choose to spend their hard-earned cash. For Sharif el Khazen, it’s where he makes it.

Read More
November 12, 2023

How Munro Will Pick Its Next Stock Winner

Munro partner and portfolio manager Kieran Moore must select a single company to pitch to an audience of industry heavyweights at the prestigious Sohn Hearts & Minds conference in Sydney.

Read More
November 12, 2023

The Australian At The Centre Of Dalio’s Bridgewater – Who Loves It

The culture at Ray Dalio’s massive hedge fund has been a source of intrigue, and with a new book, controversy. Atul Lele says it’s made him a better investor.

Read More