
Sohn Hearts & Minds is a stock picking conference, which has spun off a sharemarket fund, HM1. This year, it launched HM2, a fixed income fund, that has allocated money to six global and Australian corporate debt managers who have waived their fees so that they can be directed to medical research charities.
“There’s nothing wrong with equities guys, but they’re the leather jacket wearing optimistic 90 per cent upside guys, and that’s fine,” New York hedge fund Third Point’s Tom Anglin told the audience that is mostly filled with equity managers.
“But credit investors, we like to think we’re the more cautious and disciplined ones in the room.” Anglin asked the panellists from KKR, Eldridge, Barings and Revolution, at what stage was the private credit in the cycle – early, mid or late – with the votes split evenly between late and mid cycle.
Private credit has been in the headlines all year as losses and redemptions stack up globally and in Australia, where the industry is dominated by loans to property developers, that has been headlined by the collapse of Bathla Group.
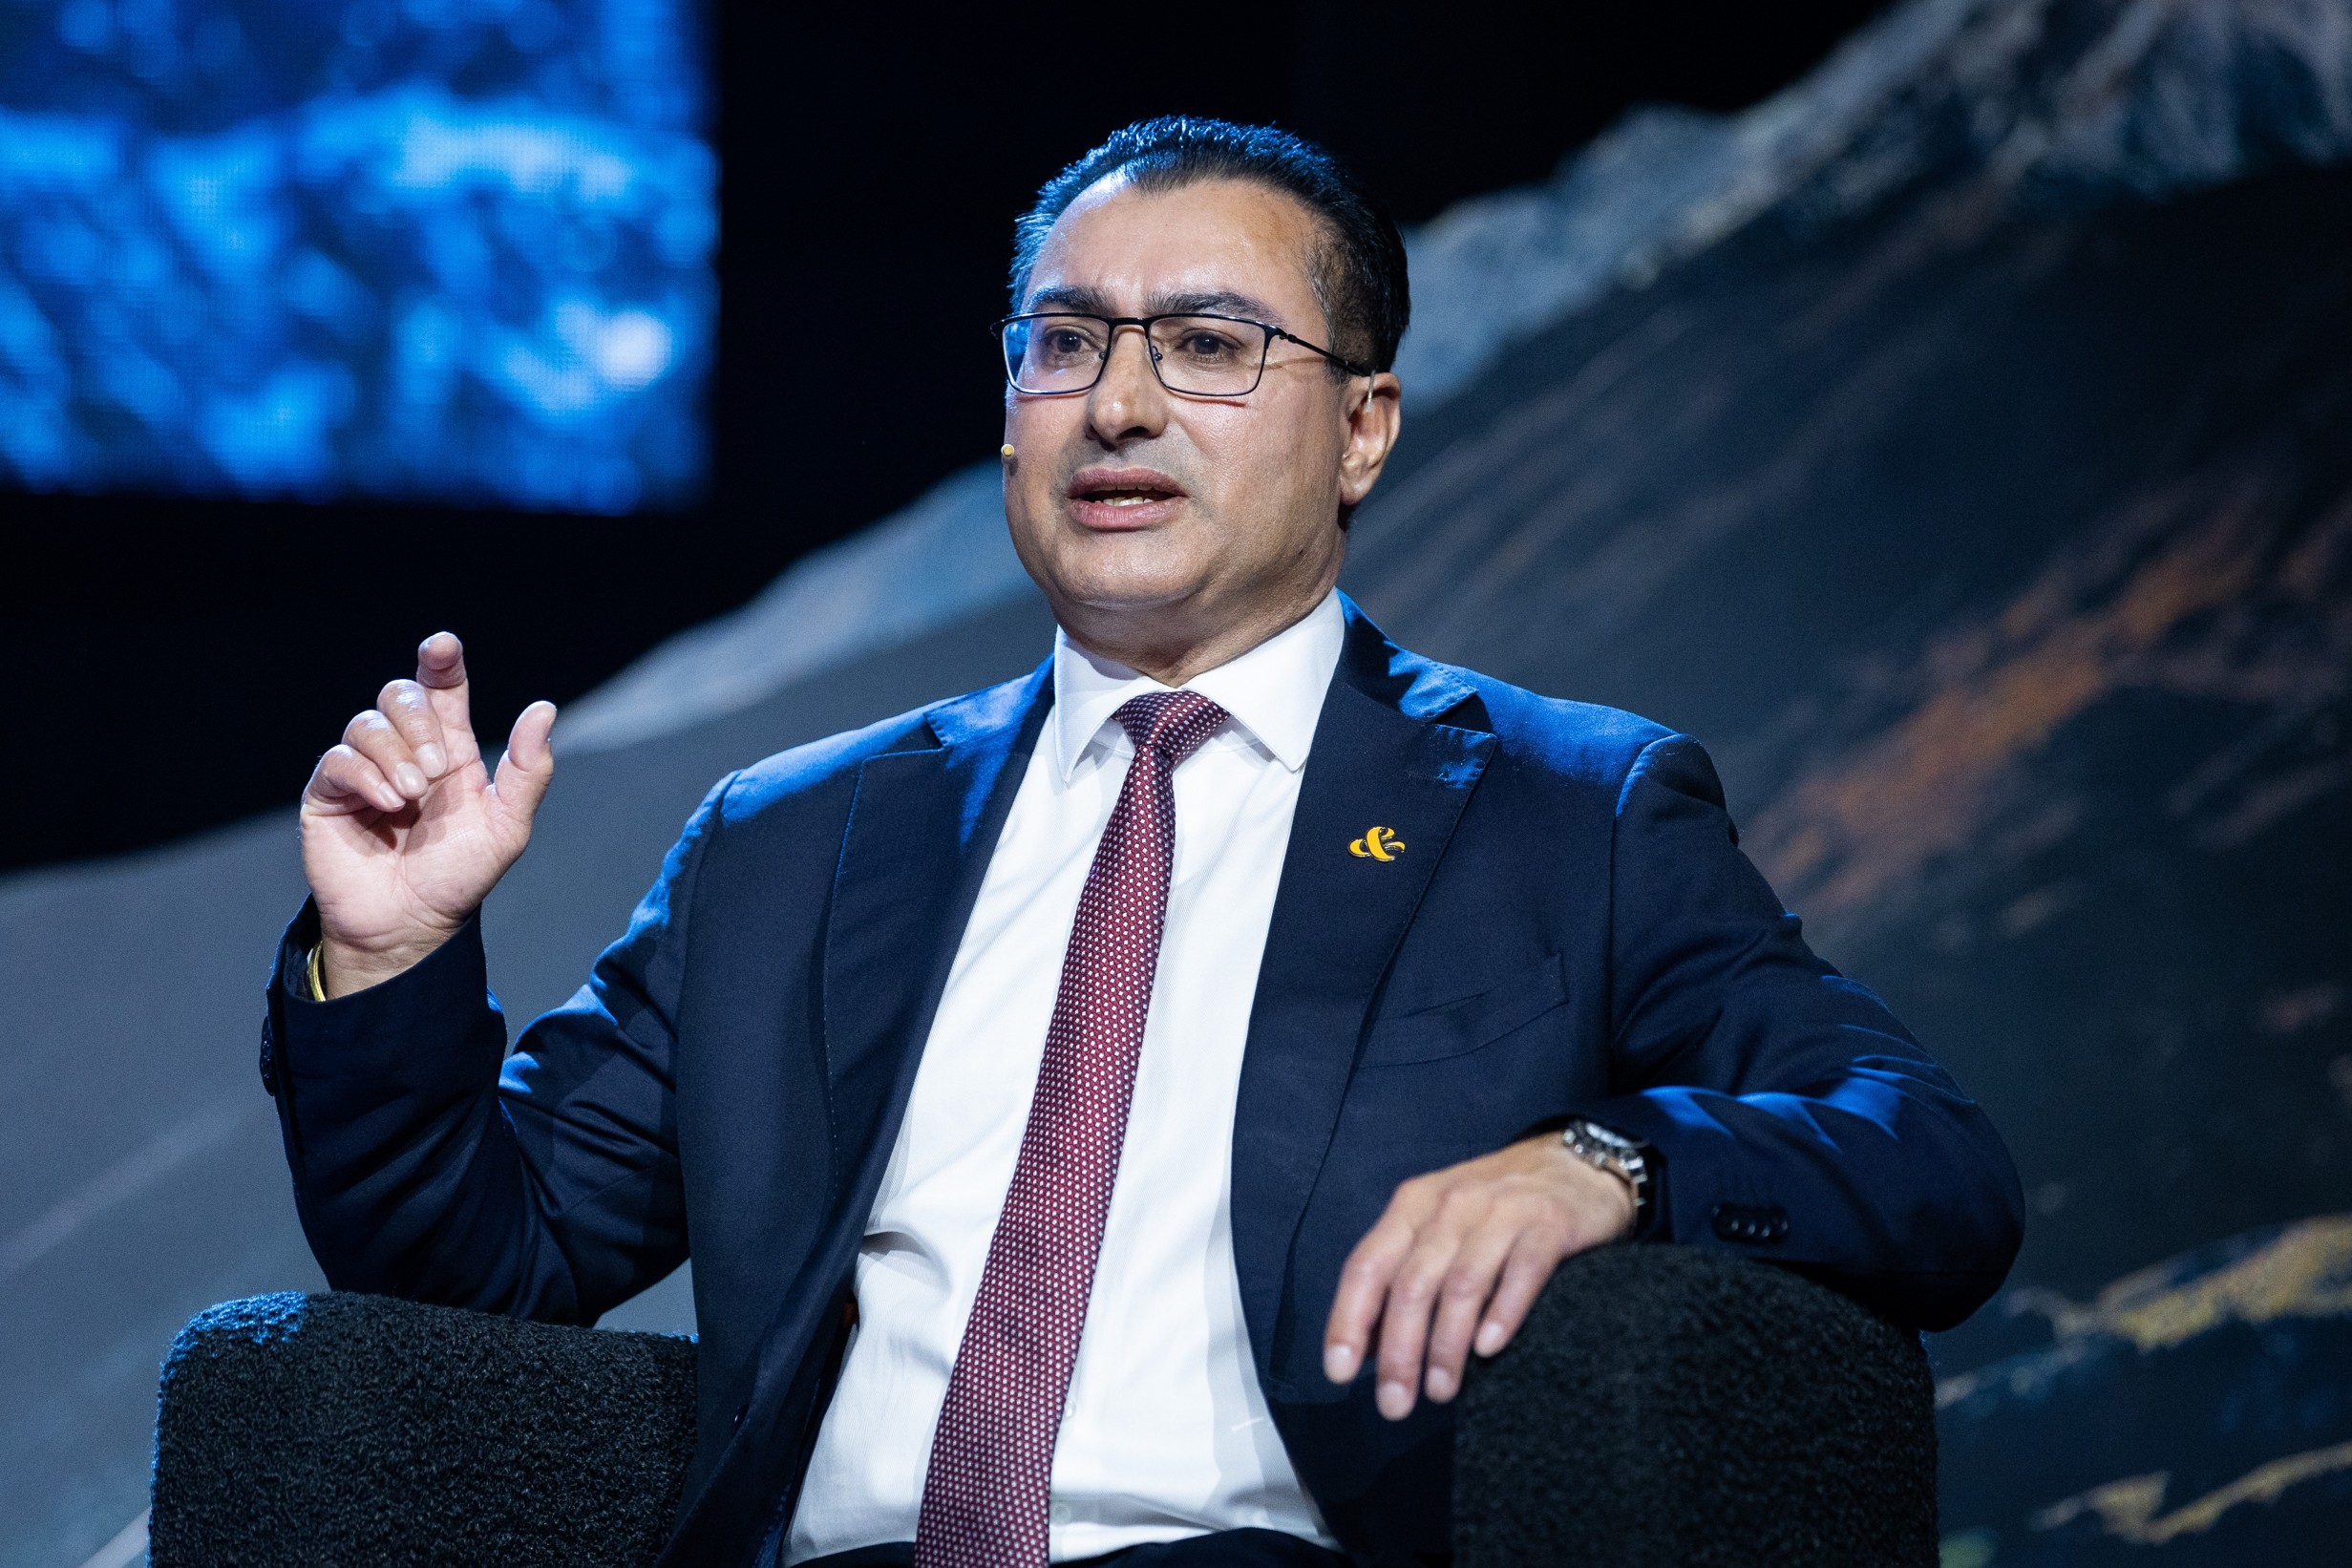
“Now it’s a year of reckoning, and we will have far less competition going forward than what we’ve had in the last five years,” Revolution Asset Management’s Bob Sahota said.
“We’ve had a long period of time where if you took a lot of risk, you look like a hero, but right about now we get to find out who’s been doing it properly.”
Sahota said the corporate regulator’s probe into private credit were “for good reason” as it identified misaligned interests around upfront and performance fees.
This article was originally posted by Australian Financial Review here. Licensed by Copyright Agency. You must not copy this work without permission.